Everything this covers.
Emergency tarping
Same-day stabilization for active openings; may be claimable under your policy's mitigation clause.
Lifted & creased shingle survey
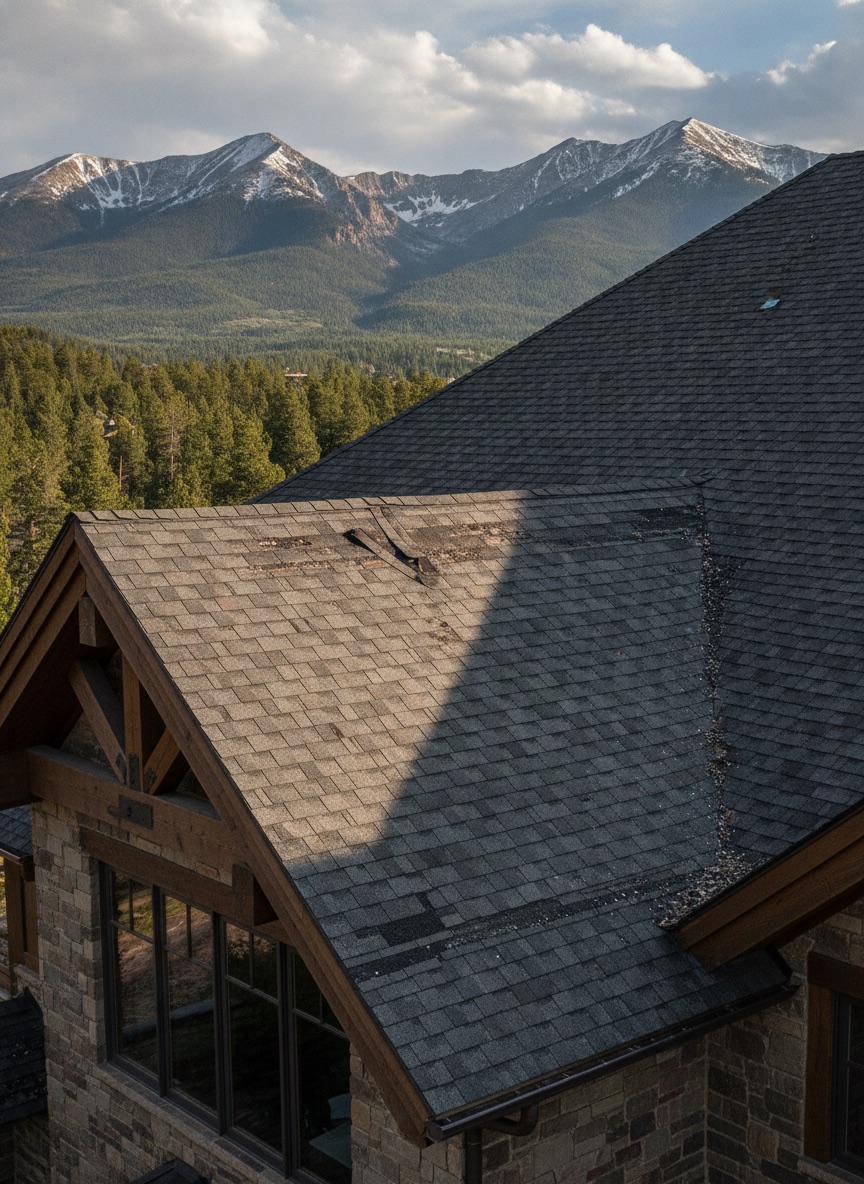
Wind damage usually shows as creases and broken seals, not missing shingles. We check the field, the edges, and the ridge.
Ridge cap & flashing check
The first components to fail in downslope winds, and the most commonly missed in adjuster scopes.
Deck and fastener assessment
Repeated uplift works fasteners loose. We check for nail pops and deck movement before they become leaks.
Wind-event documentation
Recorded gust data for your address paired with photo evidence, built for the claim file.
Matched or full replacement
When damaged shingles can't be reasonably matched, repair options become more complicated. We document material availability, repairability and existing conditions so you and your carrier can evaluate the appropriate scope.
When insurance is involved.
Wind claims follow the same weather-claim rules as hail in Colorado: filing generally can't raise your individual premium. Creased-but-attached shingles are the most under-scoped wind damage in the state, and they only get harder to document as they weather.
How claims work →Asked about
wind damage.
A few shingles blew off. Is that a claim?
Often, yes, and the visible loss is rarely the whole story. Surrounding courses often have broken seals and creases that only an on-roof inspection will find, and they belong in the documentation.
Do I need to do anything right away?
If there's an opening, yes. Tarping stops interior damage, and mitigation costs are commonly addressed by property policies. Keep every receipt.
My shingle color is discontinued. What happens?
Colorado's matching rules and most policies support full-slope or full-roof replacement when a reasonable match doesn't exist. We document material availability and existing conditions so you and your carrier can evaluate the appropriate scope.
Not sure what your roof needs? Start with information.
CHGR Roof Assessment Report™: prepared before we arrive. Verified on your roof. Reviewed with you. Yours to keep.