The first 48 hours after a hail storm
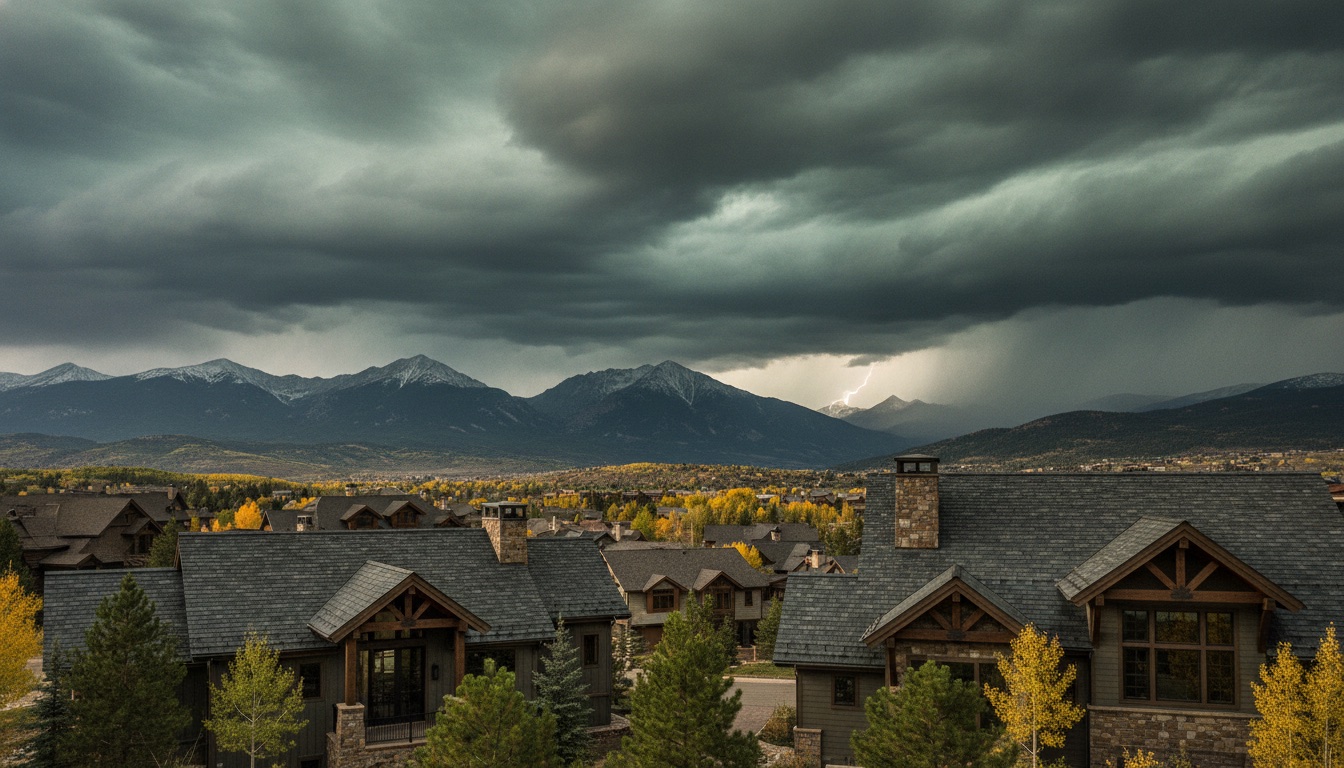
First, the good news: you have time. Most carriers allow up to 12 months to file, so nothing about a hail claim needs to be decided in a panic. The first 48 hours are about documentation and stabilization, not signatures.
Document from the ground: photograph hailstones next to a coin or tape measure, note the date and time, and walk the property for the visible tells: dented gutters and downspouts, pitted window cladding, shredded screens, stripped foliage, and granules collecting at downspout exits. Don't get on the roof; that's what we're for.
Stabilize anything actively leaking. Emergency tarping is the kind of reasonable mitigation most property policies address; keep the receipt. Then get an independent inspection before you call your carrier. Filing 'sight unseen' opens a claim record even if damage turns out to be below deductible; an inspection first means you file once, with evidence.
Finally, be careful with the knock on the door. After every major storm, out-of-state crews canvass hail-mapped neighborhoods asking homeowners to sign 'inspection agreements' that are actually assignment-of-benefits contracts. Colorado's SB38 gives you the right to choose your contractor and to cancel storm-repair contracts within 72 hours. The cleanest protection is simpler than that: don't sign anything on day one.
Questions about your roof?
Free inspection, photo report, and straight answers within 48 hours.